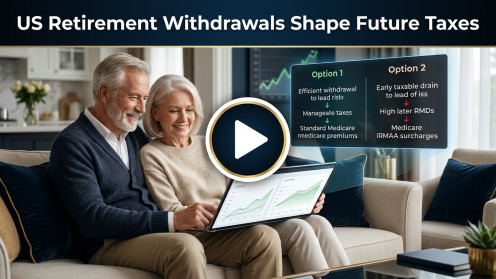
When it comes to retirement planning, the way you structure withdrawals can have a lasting impact on both your tax bill and your Medicare premiums. I’ve seen firsthand how two retirees, each with a $2.1M portfolio, can end up in very different positions—simply because of how early withdrawal decisions shape required minimum distributions (RMDs) and future Medicare surcharges. For example, splitting your savings between taxable accounts and a traditional IRA might generate $117,400 in annual income, but where those assets are held determines both current tax efficiency and future tax pressure. For joint filers in 2026, keeping your modified adjusted gross income (MAGI) at or below $218,000 means you’ll stick with standard Medicare premiums, but just one extra dollar can push you into higher brackets, with Part B jumping by nearly $284, plus additional Part D surcharges. Many people are surprised to learn that draining taxable accounts first may allow IRA balances to grow—potentially leading to larger RMDs down the road. On the other hand, strategic IRA withdrawals or conversions before RMD age could help reduce future tax and Medicare pressures. As year-end approaches, it’s wise to model possible RMD paths, keep Roth conversions below the next IRMAA threshold, and review your IRA holdings for risks like floating-rate, leverage, and concentration. My approach to retirement is always about protecting assets, minimizing taxes, and ensuring your Medicare choices support your long-term financial security.
Leave a Reply